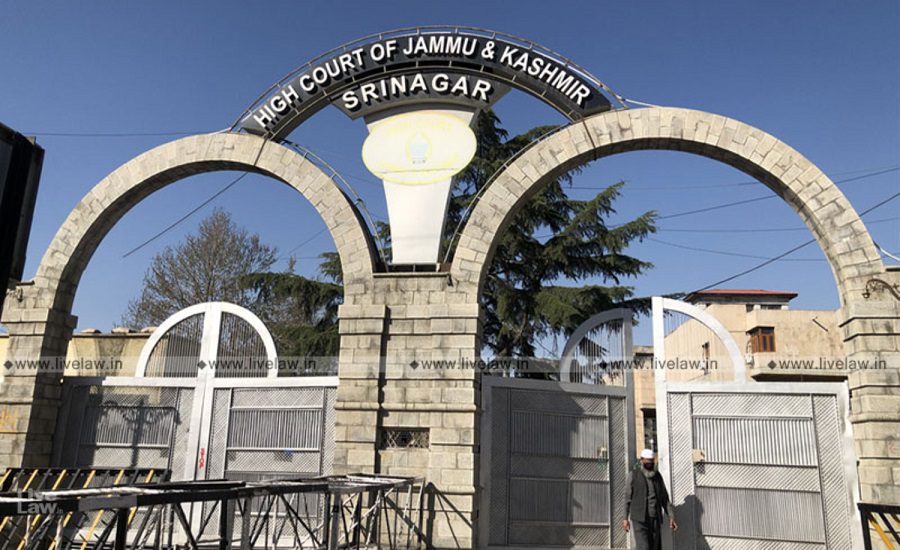
Ladakh: On November 29, 2025, the Jammu & Kashmir and Ladakh High Court delivered a landmark decision in the case M/S New Gee Enn & Sons v Union of India & Ors., ruling that trade conducted across the Line of Control (LoC) between the Union Territory of Jammu & Kashmir (J&K) and the region under de facto control of Pakistan — commonly referred to as Pakistan‑Occupied Kashmir (PoK) — qualifies as intra-state trade under the Central Goods and Services Tax Act 2017 (CGST Act) and related GST framework.
This ruling has far-reaching implications for taxation, legal classification of cross-LoC transactions, and the status of PoK under Indian law. But beyond legal semantics, it raises larger constitutional and territorial questions.
Background of the Cross-LoC Trade
Since 2008, under a confidence-building measure between India and Pakistan, barter trade was allowed across the LoC on specified routes — namely Srinagar–Muzaffarabad and Poonch–Rawalakote. This was regulated by a government-issued Standard Operating Procedure (SOP).
Read also: J&K Arms Licence Scam Case: High Court Awaits Final Call from Home Ministry on IAS Officers
The trade was barter-based: goods, not currency, changed hands. This was meant to benefit local economies on both sides of the divide.
Under the earlier tax regime (the Jammu and Kashmir Value Added Taxes Act, 2005), this cross-LoC trade had been treated as zero-rated intra-state sale when it was first undertaken.
However, with the rollout of GST in 2017 — including the Central GST Act and the regional J&K GST Act — traders carried on with cross-LoC trade without paying GST, likely believing their trade remained intra-state.
In 2019, cross-LoC trade was suspended, amid concerns and allegations about misuse of trade corridors for illicit activities such as smuggling of weapons, narcotics and fake currency.
In the aftermath, tax authorities began scrutinizing past transactions. For the financial years 2017-2018 and 2018-2019, several traders were issued show-cause notices under Section 74(1) of the CGST Act, alleging “huge outward and inward supplies” for which GST had not been declared in returns.
These traders challenged the notices via writ petitions under Article 226 of the Constitution, arguing that;
(1) cross-LoC barter trade was regulated under the 2008 SOP and hence not subject to GST; (2) show-cause notices were barred by limitation;
(3) since barter trade involves no currency exchange, taxing both outward and inward supplies would amount to double taxation
(4) trade between the UT (J&K) and PoK cannot be treated as inter-state or international supply.
High Court’s Reasoning: Why Cross-LoC Trade Is “Intra-State”
A Division Bench comprising Justice Sanjeev Kumar and Justice Sanjay Parihar undertook a careful examination of legal, constitutional, and factual aspects. Key observations and conclusions:
Territorial Identity: The Court affirmed that the region currently under de facto control of Pakistan (PoK) remains part of the territories of the erstwhile State of Jammu & Kashmir, under Indian constitutional and legal frameworks.
Location of Supplier & Place of Supply: Given that both supplier (in J&K UT) and place of supply (in PoK) lie within the same legal territorial entity (the erstwhile state, now reorganised UT), the trade qualifies as intra-state supply under Section 8 of the Integrated Goods and Services Tax Act, 2017 (as read with the CGST Act).
GST Applicability & Exemption Absence: The Court noted there was no specific notification under Section 11 of CGST Act exempting cross-LoC barter trade from GST. Therefore the supplies (both inward and outward) were taxable supplies. Traders were bound to self-assess and declare GST while filing returns.
Limitation & Validity of Notices: The show-cause notices under Section 74(1) of CGST Act focused on alleged suppression of outward supplies — a ground which makes limitation applicable up to five years from due date for filing annual returns. The Bench held the notices were issued in time and not barred by limitation.
Bunching of Periods: A composite notice spanning two tax years (2017–18 & 2018–19) was upheld as valid. The Court observed that GST law does not prohibit consolidation of tax periods for demand, provided the notice is specific and not vague or indefinite.
Statutory Remedies over Writ Jurisdiction: Although the traders had sought writ relief under Article 226, the Court declined to interfere at this stage, noting the availability of efficacious statutory remedies (appeal under Section 107 of CGST Act) after adjudication.
Ultimately, the Court dismissed the writ petitions, but granted “partial relief”: traders who had not replied to notices were given 4 weeks to respond; where final orders confirming demand were passed, traders were given 3 months to file appeals under Section 107.
Key Significance & Implications of the Ruling
Legal & Taxation Impact: The verdict clarifies that cross-LoC trade (under the 2008 SOP) is to be treated as intra-state under GST law — subject to CGST/SGST — and not as inter-state or international trade. This removes ambiguity on classification under GST and affirms taxable liability.
Traders who previously refrained from declaring GST on cross-LoC barter transactions will now need to reckon with retrospective tax liabilities, potentially with interest and penalties.
The judgment sets a precedent for interpretation of “place of supply” and “location of supplier” in ambiguous territorial contexts — especially where the constitutional status of regions under de facto foreign control is contested.
Political / Constitutional Implications: By affirming that PoK remains legally part of the territory of the erstwhile State of Jammu & Kashmir, the Court’s ruling reiterates India’s territorial claim over PoK — bolstering the constitutional position vis-à-vis Pakistan.
The decision underscores that administrative or de facto control does not alone define the legal boundaries under Indian law.
For Trade, Commerce & Former Traders: For traders involved in cross-LoC barter trade (or previously doing so), this creates a significant financial and legal concern — potential tax liabilities for past transactions.
The ruling may deter any future push to revive cross-LoC trade, given the tax burden and legal uncertainties, especially in light of security concerns that led to suspension in 2019.