New Delhi: Indraprastha Gas Limited (IGL) reported a sharp decline in consolidated profitability for the second quarter of FY27, despite recording growth in sales volumes and revenue. The city gas distribution company reported consolidated Profit After Tax (PAT) of ₹23.75 crore for the quarter ended September 30, 2026, compared with ₹384.95 crore in the corresponding quarter of the previous financial year.
The company’s performance was affected by higher natural gas procurement costs and significant pressure on operating margins. Despite the increase in sales volumes, IGL reported negative Earnings Before Interest, Taxes, Depreciation and Amortisation (EBITDA) of ₹31.11 crore during the quarter.
IGL announced its unaudited financial results for the quarter and half-year ended September 30, 2026. The results were reviewed by the company’s Statutory Auditors and received an unmodified review conclusion.
IGL Q2 FY27 Financial Results: Profitability Declines Sharply
IGL’s consolidated financial performance reflected a significant decline in profitability during Q2 FY27. Profit Before Tax (PBT) stood at ₹9.03 crore, compared with ₹487.63 crore in the corresponding quarter last year.
The company reported total comprehensive income of ₹24.17 crore for Q2 FY27, against ₹384.96 crore in Q2 FY26.
For the first half of FY27, consolidated PAT stood at ₹261.67 crore, compared with ₹812.75 crore in the corresponding period of the previous financial year. PBT for H1 FY27 was ₹320.75 crore, against ₹1,035.38 crore in H1 FY26.
Key consolidated financial highlights include:
- Profit Before Tax (Q2 FY27): ₹9.03 crore, compared with ₹487.63 crore in Q2 FY26.
- Profit After Tax (Q2 FY27): ₹23.75 crore, against ₹384.95 crore in Q2 FY26.
- Total Comprehensive Income (Q2 FY27): ₹24.17 crore, compared with ₹384.96 crore.
- Profit Before Tax (H1 FY27): ₹320.75 crore, against ₹1,035.38 crore in H1 FY26.
- Profit After Tax (H1 FY27): ₹261.67 crore, compared with ₹812.75 crore.
- Total Comprehensive Income (H1 FY27): ₹261.14 crore, against ₹812.68 crore.
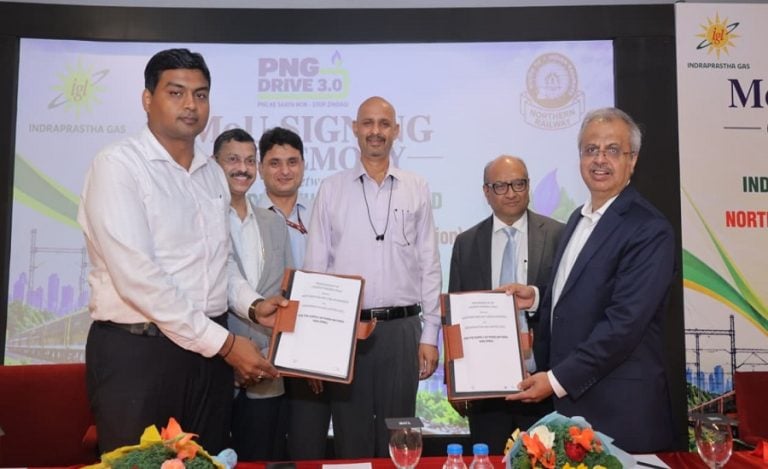
Read also: IGL Signs MoU with Northern Railway to Supply PNG Across 22 Railway Establishments in Delhi-NCR
IGL Sales Volumes Rise 8% to 925.59 MMSCM in Q2 FY27
Despite pressure on profitability, IGL recorded healthy growth in sales volumes during the September quarter. Total sales volumes increased 8% year-on-year to 925.59 million standard cubic metres (MMSCM).
CNG remained the largest contributor to the company’s sales volumes, while domestic PNG recorded the highest percentage growth among the three reported segments.
The segment-wise sales volume performance was as follows:
- CNG: 696.63 MMSCM, registering 9% year-on-year growth.
- PNG – Domestic: 73.31 MMSCM, increasing 16% year-on-year.
- PNG – Industrial/Commercial: 109.35 MMSCM, registering 2% growth.
- Total Sales Volumes: 925.59 MMSCM, up 8% year-on-year.
The increase in sales volumes highlights continued demand across IGL’s city gas distribution network. However, higher volumes did not translate into improved profitability during the quarter due to rising input costs.
IGL Revenue from Operations Increases 27% to ₹5,116 Crore
IGL recorded growth in revenue during Q2 FY27. Net revenue from operations increased 27% year-on-year to ₹5,116.23 crore.
The company’s gross revenue from operations stood at ₹5,613.62 crore during the quarter.
However, the increase in revenue was accompanied by higher natural gas procurement costs, which affected operating margins and overall profitability. The company reported negative EBITDA of ₹31.11 crore, indicating continued pressure on its core operating performance.
Higher Natural Gas Costs Put Pressure on Operating Margins
The sharp decline in IGL’s profitability, despite higher sales volumes and revenue, was primarily attributed to significantly higher natural gas purchase costs during the quarter.
The company’s negative EBITDA highlights the pressure on its operating economics, as operating expenses exceeded operating earnings during the period.
The gap between volume growth and profitability also underlines the importance of gas procurement costs, input prices and selling margins in the city gas distribution business.
Investors will be monitoring whether IGL can improve its procurement economics and operating margins in the coming quarters.
₹330 Crore DDA Liability Remains in Focus
Apart from its quarterly financial performance, investors are also tracking a contingent liability of approximately ₹330 crore linked to a dispute with the Delhi Development Authority (DDA) over land licence fees.
The dispute remains an additional factor for investors assessing the company’s potential financial obligations and overall outlook. Its eventual financial implications will depend on the outcome of the matter.
IGL Q2 FY27 Results Highlight Challenges Despite Volume Growth
IGL’s Q2 FY27 performance highlights the challenges facing the city gas distribution sector amid rising input costs. Although the company recorded 8% growth in sales volumes and a 27% increase in net revenue from operations, its profitability declined sharply and EBITDA turned negative.
The company’s ability to manage natural gas procurement costs, improve operating margins and address the DDA-related liability will remain important factors for investors in the coming quarters.
The Board meeting to consider the financial results commenced at 3:40 p.m. and concluded at 6:30 p.m.
About Indraprastha Gas Limited (IGL)
Indraprastha Gas Limited (IGL) is a leading city gas distribution company in India. It supplies Compressed Natural Gas (CNG) for vehicles and Piped Natural Gas (PNG) to domestic, industrial and commercial consumers. The company operates primarily in Delhi and the surrounding National Capital Region, supporting the expansion of natural gas infrastructure and cleaner fuel adoption.
Read also: IGL’s CNG Recompression Case Study Recognised at 1st PNGRB National Sustainability Conference