By P Sesh Kumar
India has set itself an ambitious goal of becoming a global economic powerhouse. It wants Indian companies to compete with multinational corporations, Indian professionals to lead international industries, and domestic institutions to shape global standards. Yet, amid these aspirations, one of the country’s oldest and most respected professions finds itself facing an uncomfortable question: can India truly build world-class accounting firms while its own regulatory framework continues to place domestic players at a structural disadvantage?
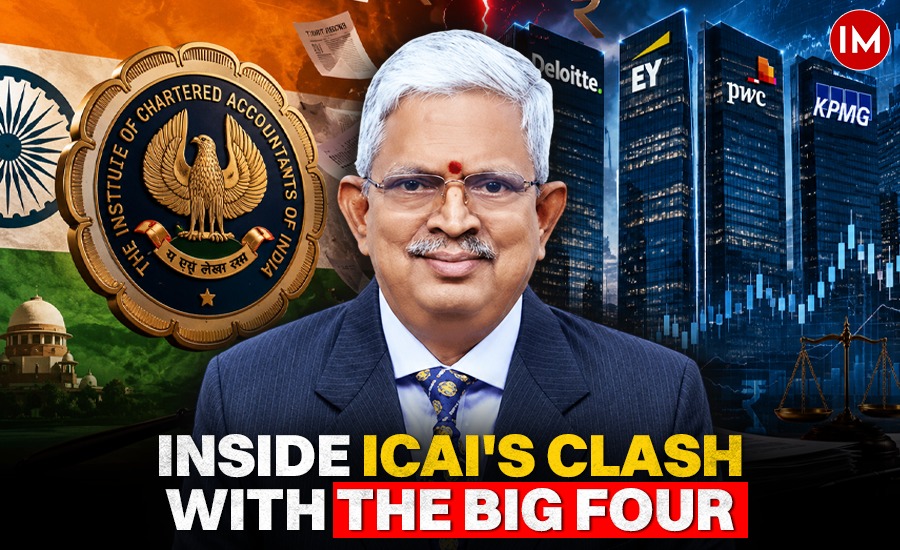
This question has come sharply into focus following the controversy surrounding the Institute of Chartered Accountants of India’s (ICAI) Global Networking Guidelines, 2025. At first glance, the debate appears to revolve around technical regulations governing professional networking arrangements. In reality, it has evolved into a much larger contest over transparency, competition, regulatory authority and the future of India’s professional services industry.
On one side are the global accounting giants—Deloitte, EY, PwC and KPMG—whose Indian operations have become some of the fastest-growing parts of their worldwide businesses. On the other are more than one lakh Indian Chartered Accountant firms, the overwhelming majority of which remain relatively small partnerships competing in an increasingly unequal marketplace. What began as an attempt to bring greater clarity to global affiliations has now exposed deeper questions about how India wants its accounting profession to evolve.
A Law Written for a Different India
To understand why the issue has become so contentious, one has to revisit the origins of the profession itself. When Parliament enacted the Chartered Accountants Act in 1949, India had only recently become independent. The legislation was designed to establish a credible, self-regulated profession built on integrity, independence and public confidence. It created the Institute of Chartered Accountants of India as the profession’s regulator and introduced a Code of Ethics that would govern every practising Chartered Accountant.
The philosophy behind the law was clear. Chartered accountants were expected to function as trusted professionals rather than commercial enterprises. Over the decades, this philosophy translated into strict restrictions that prohibited firms from advertising their services, soliciting clients, raising external capital or forming partnerships with professionals outside the Chartered Accountancy profession. While these rules helped preserve professional independence, they also limited the ability of Indian firms to expand into multidisciplinary organisations capable of competing with large international consulting networks.
As global professional services evolved, Indian firms largely remained small partnerships. Even today, despite having over one lakh registered CA firms across the country, fewer than 400 firms reportedly have more than ten partners. Most continue to operate in areas such as statutory audit, taxation, GST compliance and accounting services, with limited opportunities to scale into large integrated advisory firms.
The Liberalisation Era Changed Everything
Economic liberalisation in 1991 transformed the Indian economy and opened new opportunities for multinational professional service firms. Global accounting giants entered India to provide consultancy services, as the law did not permit foreign entities to directly undertake statutory audits or practise accountancy.
Instead of challenging the legal framework, these firms developed an alternative operating model. They established relationships with Indian Chartered Accountant firms that would remain legally independent but become part of broader international networks. Over time, entities such as SR Batliboi & Co. became associated with EY, BSR & Co. with KPMG, while Deloitte and PwC also developed extensive affiliate structures across the country.
Legally, audit reports continued to be signed by Indian Chartered Accountants working through Indian partnerships. Operationally, however, these firms increasingly functioned as integral components of global organisations. Technology, methodologies, branding, training systems and client servicing gradually became deeply interconnected with their international networks.
Over the years, even ICAI’s own committees described many of these arrangements as methods of circumventing the spirit of existing regulations, even if they technically complied with Indian law.
India Became a Growth Engine for the Big Four
Three decades later, the scale of these operations has become impossible to ignore. India has emerged as one of the fastest-growing markets for the Big Four globally. Their combined Indian revenues reached approximately ₹38,500–38,800 crore during FY2024 and are projected to exceed ₹45,000 crore in FY2025.
Each firm has recorded impressive growth. EY India’s revenues crossed ₹13,400 crore after growing by around 16–17 per cent. Deloitte India touched ₹10,000 crore following nearly 29 per cent growth, while PwC India expanded to roughly ₹9,200 crore after registering 22 per cent growth.
What makes these numbers even more remarkable is that auditing now represents only a relatively small share of their Indian business. Consulting, digital transformation, taxation, mergers and acquisitions, technology advisory and other professional services account for the majority of their revenues. Deloitte India, for instance, reportedly derives more than 60 per cent of its income from consulting alone.
This transformation has fundamentally altered the competitive landscape. For many large Indian corporations and multinational companies operating in the country, the Big Four have become the preferred destination not only for auditing but also for complex advisory assignments, technology consulting and business transformation projects.
ICAI’s Attempt to Bring Greater Transparency
As the influence of global networks continued to expand, questions about regulatory oversight became increasingly difficult to ignore. The issue eventually reached the Delhi High Court, which, in July 2024, affirmed that ICAI possessed the authority to regulate such arrangements while directing the Institute to develop a formal framework governing global networking structures.
Responding to this direction, ICAI’s 40-member Council—which includes 32 elected Chartered Accountants and eight government nominees—approved the ICAI (Global Networking) Guidelines, 2025. The guidelines were notified in the Gazette of India on 11 February 2026 and came into effect six days later.
Also read: Government e-Marketplace: India’s Procurement Revolution Under the Auditor’s Lens (Part I)
Contrary to some initial perceptions, the guidelines were not designed to prevent Indian firms from joining global networks. In fact, they sought to provide legal clarity and formal recognition to such affiliations. Indian firms would now be able to openly identify themselves as part of international networks instead of functioning through arrangements that had remained legally ambiguous for decades.
However, legitimacy came with one important condition: transparency.
The new framework required every global networking arrangement to formally register with ICAI. More significantly, affiliated firms were expected to disclose the commercial agreements governing their relationships with international networks. These agreements included royalty payments, brand licensing arrangements, technology-sharing mechanisms and other financial terms that had traditionally remained confidential.
The guidelines also required every network to appoint a nodal officer who would be responsible for ensuring compliance with Indian regulations. Annual returns detailing revenue, foreign payments, staff strength and disciplinary proceedings were to be submitted regularly. Commercial transactions between Indian affiliates and global networks were expected to follow the principle of arm’s-length dealings, and non-compliance could amount to professional misconduct under the Chartered Accountants Act.
Why the Big Four Objected
Although ICAI viewed these requirements as essential for improving transparency, they triggered immediate concern among the Big Four and other large consultancy networks.
Their primary objection centred on confidentiality. The commercial agreements governing relationships between Indian affiliates and their global parent organisations contain information relating to royalty payments, technology licensing, branding arrangements and fee-sharing structures. These firms argued that submitting such agreements to ICAI posed significant commercial risks, particularly because many members of ICAI’s governing Council are themselves practising Chartered Accountants running competing firms.
Equally contentious was the requirement that dealings between Indian affiliates and global networks be conducted on an arm’s-length basis. The firms argued that multinational professional service organisations function through deeply integrated systems where technology platforms, quality control mechanisms, training programmes and operational methodologies are shared across jurisdictions. Imposing strict arm’s-length standards, they believed, failed to reflect the realities of modern global professional networks.
Another major concern related to the proposed role of the nodal officer. Senior partners feared they could become personally liable for compliance failures involving overseas entities over which they exercised little direct operational control. For many within the global networks, this created an unacceptable level of legal exposure.
As a result, what had initially appeared to be a technical regulatory reform quickly transformed into one of the most significant confrontations the Indian accounting profession has witnessed in decades. Beneath the debate over forms, disclosures and compliance requirements lay a much larger struggle over market dominance, regulatory authority and the future structure of India’s professional services industry. When the Battle Moved Beyond ICAI
The notification of the ICAI (Global Networking) Guidelines in February 2026 should have marked the beginning of a new regulatory framework for India’s accounting profession. Instead, it triggered an intense contest that quickly moved beyond ICAI’s Council chambers into the corridors of the Ministry of Corporate Affairs (MCA) and, eventually, the highest levels of government.
Unlike many corporate disputes, this confrontation did not unfold through dramatic courtroom battles or public campaigns. It was largely fought behind closed doors through consultations, representations and policy discussions. The Big Four firms chose a quieter approach, engaging directly with policymakers to convey their concerns over the new framework.
Representatives of several global accounting firms argued before MCA officials that the mandatory disclosure of commercial agreements would expose highly confidential business information. Their concern was not merely about regulatory compliance but also about who would have access to that information. Since ICAI’s governing Council consists largely of practising Chartered Accountants who also operate competing firms, the global networks questioned whether commercially sensitive arrangements relating to royalty payments, technology licensing, branding agreements and revenue-sharing structures could remain adequately protected.
These concerns soon found resonance within the Ministry of Corporate Affairs. The ministry is understood to have advised ICAI to first address stakeholder concerns before moving ahead with full implementation of the guidelines. During ICAI Council deliberations held in June and July 2026, discussions reportedly centred on whether the framework should be deferred or modified. Perhaps the strongest indication of the growing discomfort was that although the guidelines had already been notified through the Gazette of India, they were never uploaded on ICAI’s official website. What had initially appeared to be a landmark regulatory reform suddenly found itself in administrative limbo.
The Government’s Contradictory Position
The controversy also exposed an apparent contradiction in the government’s broader approach towards India’s professional services sector.
Over the past several years, the Union Government has repeatedly spoken about creating globally competitive Indian accounting firms capable of challenging multinational networks. The Prime Minister’s Office has reportedly held multiple discussions since 2017 on strengthening domestic professional services, while Finance Minister Nirmala Sitharaman has publicly encouraged ICAI to develop “Indian Big Four” firms that can compete internationally. Discussions have also explored lessons from countries like China, where state-owned enterprises have increasingly shifted towards domestic audit firms in strategic sectors.
National security concerns have added another dimension to this debate. The PMO has examined the possibility of limiting the participation of foreign-linked accounting firms in auditing Public Interest Entities operating in sectors such as banking, defence, telecommunications, energy and space because of concerns relating to sensitive corporate data and cross-border information flows.
Yet, while these long-term objectives suggest a desire to strengthen domestic firms, the government’s handling of the ICAI guidelines appeared to send a different signal. By intervening after objections were raised and encouraging a reconsideration of the framework, the same government that had advocated building strong Indian professional firms was also seen as slowing down one of ICAI’s most significant attempts to increase transparency in global networking arrangements.
This contradiction lies at the heart of the present controversy. It is difficult to simultaneously advocate self-reliance in professional services while delaying reforms designed to create a more level playing field for domestic firms.
The Unequal Playing Field for Indian Firms
For thousands of small and medium-sized Chartered Accountant firms across the country, this debate is far more than a regulatory disagreement. It is about survival in a market where competitive conditions have increasingly favoured a handful of large global networks.
India today has more than one lakh registered CA firms. Yet, the Big Six—the Big Four along with Grant Thornton and BDO—account for a disproportionately large share of audits involving listed companies. As of March 2025, these firms reportedly handled nearly one-third of all NSE-listed company audits and more than 300 of the Nifty 500 audit mandates. EY alone accounted for 176 Nifty 500 audits.
Such concentration has naturally widened the gap between multinational-affiliated firms and independent domestic practices.
The challenge extends well beyond auditing. Global networks possess enormous financial resources that allow them to invest heavily in technology, artificial intelligence, digital consulting platforms, specialised training and international knowledge systems. They also benefit from globally recognised brands that attract multinational clients and some of the country’s brightest young professionals.
For smaller Indian firms, competing against these advantages has become increasingly difficult.
Until recently, they were prohibited from advertising their expertise or promoting their services in ways that global consulting networks could indirectly accomplish through conferences, thought leadership publications, technology partnerships and consulting brands. Although ICAI has now liberalised several advertising norms under the revised Code of Ethics effective from April 2026, many practitioners believe the competitive imbalance created over several decades cannot be corrected overnight.
The Talent Drain
Perhaps the most significant consequence of this imbalance is the growing concentration of talent within a few large organisations.
Every year, India’s Chartered Accountancy examination produces thousands of highly qualified professionals. Many of the most talented graduates naturally aspire to join the Big Four because of better salaries, international exposure, sophisticated technology platforms and opportunities to work with multinational clients.
From there, many professionals eventually move into investment banking, private equity, multinational corporations, global capability centres and corporate leadership positions.
While this reflects the success of India’s accounting talent, it also creates challenges for independent Indian firms that struggle to retain experienced professionals.
PwC US alone reportedly plans to increase its India workforce to around 80,000 employees by 2028. Such expansion illustrates the growing scale of global professional networks in India but simultaneously raises questions about whether domestic firms can realistically compete for talent under existing regulatory and financial constraints.
Lessons from Around the World
India is by no means the first country to grapple with the dominance of the Big Four.
The United Kingdom has spent years examining the concentration of audit markets. Following concerns over corporate failures and declining competition, the Competition and Markets Authority proposed operational separation between audit and consulting businesses while encouraging greater participation by challenger firms. Although implementation has been gradual, the reforms sought to improve both independence and market diversity.
The European Union adopted mandatory audit rotation and imposed restrictions on certain non-audit services in an effort to reduce conflicts of interest and encourage greater competition. While these measures strengthened auditor independence, studies cited in the source material suggest they produced only modest improvements in overall market concentration.
Australia has also examined ways to broaden competition within its audit market, while China has adopted perhaps the strongest approach by encouraging state-owned enterprises to reduce reliance on multinational audit firms and increasingly engage domestic alternatives.
Despite the differences in regulatory models, one common lesson emerges from international experience. Transparency is generally regarded as the first step towards meaningful reform. Countries seeking to diversify their professional services ecosystem typically begin by improving disclosure, clarifying ownership structures and strengthening regulatory oversight before attempting more fundamental structural changes.
A Reform Opportunity That Should Not Be Lost
The controversy surrounding the Global Networking Guidelines should not be viewed simply as a contest between ICAI and the Big Four. It presents an opportunity to rethink the broader architecture of India’s professional services industry.
Withdrawing the guidelines altogether would represent a missed opportunity. Instead, legitimate concerns relating to commercial confidentiality and personal liability could be addressed through carefully designed safeguards. Sensitive commercial information, for instance, could be handled through specialised regulatory mechanisms with stronger confidentiality protections, while liability provisions for nodal officers could be refined to reflect practical operational realities.
However, transparency alone will not be enough to transform the profession.
If India genuinely wishes to create globally competitive domestic accounting firms, broader reforms may become necessary. These include examining whether Chartered Accountant firms should be permitted to raise external capital, encouraging multidisciplinary partnerships involving lawyers, technology professionals and actuaries, and revisiting procurement practices that often favour firms with large international footprints.
Equally important is the need for greater consistency in public policy. The ambition to create an “Indian Big Four” cannot remain confined to speeches and policy discussions. It requires regulatory choices that actively support the growth of domestic firms while ensuring fair competition for all participants.
A Defining Test for India’s Reform Agenda
The debate over ICAI’s Global Networking Guidelines ultimately reflects a larger question confronting India’s economic reforms. The country frequently speaks about self-reliance, building national champions and reducing dependence on foreign-controlled institutions in strategic sectors. Yet whenever reforms begin to alter existing market structures, competing commercial interests often slow the pace of change.
The accounting profession has become a mirror of this broader contradiction.
The Global Networking Guidelines were never intended to dismantle international professional networks. They sought to bring greater clarity and transparency to arrangements that have evolved over more than three decades. Whether those objectives are ultimately realised will depend not only on ICAI but also on the government’s willingness to reconcile its aspiration of building globally competitive Indian firms with the difficult regulatory decisions necessary to achieve that goal.
For India’s one lakh Chartered Accountant firms and more than four lakh practising professionals, the outcome will shape far more than professional regulation. It will determine whether India’s accounting profession continues to operate under a system that many believe favours a few dominant global networks or moves towards a more transparent and competitive future where domestic firms have a genuine opportunity to grow into global champions.
About The Author– (Mr. P Sesh Kumar is a retired 1982-batch officer of the Indian Audit and Accounts Service (IA&AS) who served as Director General of Audit at the Comptroller & Auditor General of India.)
Disclaimer – (The views and opinions expressed in this article are solely those of the author and do not necessarily reflect the views of Indian Masterminds. For feedback or queries, please write to [email protected].)
Also read: Government e-Marketplace: India’s Procurement Revolution Under the Auditor’s Lens (Part II)