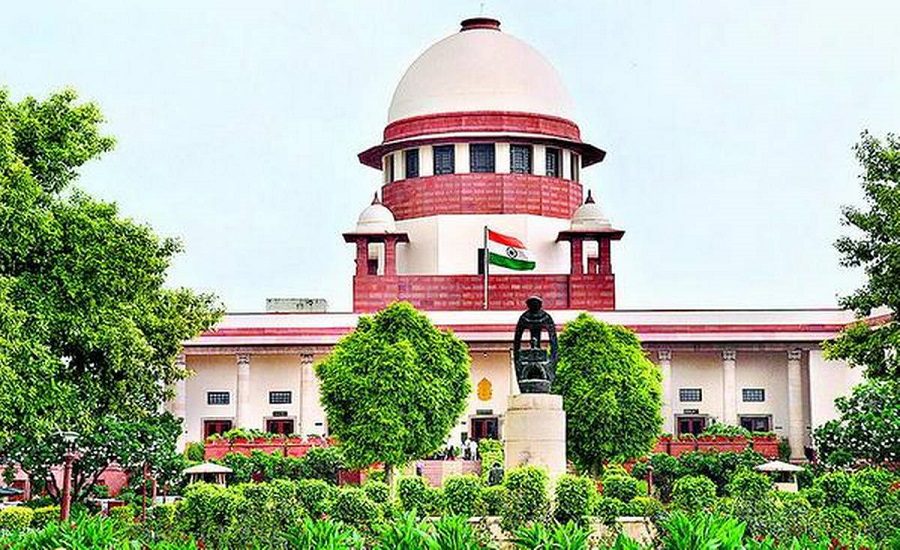
In a significant tax-law development, the Supreme Court of India (SC) has taken up the question of whether a trust’s registration under Section 12AA of the Income Tax Act, 1961 automatically entitles donors to claim tax deductions under Section 80G of the Act. This ruling could have far-reaching implications for charitable trusts in India, donations made by taxpayers, and the way the tax-department evaluates trust activities going forward.
Background of the Section 12AA Controversy
Under the Income Tax Act, two key provisions apply to charitable institutions and their donors:
- Section 12AA provides for registration of trusts or institutions for charitable or religious purposes, thereby granting them tax-exemption status for their income.
- Section 80G allows donors to claim deduction from their taxable income when they donate to approved trusts/institutions.
The controversy arises because while 12AA registration recognises a trust’s charitable status, 80G approval involves additional scrutiny of the trust’s objectives and activities (particularly whether they are truly “charitable” and not primarily religious or sectarian). In one case, the tax department challenged the view that 12AA registration alone suffices for 80G benefits.
In the matter before the SC — The Commissioner of Income Tax (Exemption), Bhopal vs. Sadhumargi Shantkranti Jain — the respondent trust had registration under 12AA but its 80G application was rejected by the CIT(Exemption) because the trust engaged in religious activities. The trust’s appeal was allowed by the ITAT and the High Court. The Revenue department now challenges that decision before the SC.
What Is the Issue for the Supreme Court?
The core question for the SC bench (headed by J. B. Pardiwala and K. V. Viswanathan) is that does the mere registration of a trust under Section 12AA entitle its donors to automatic deduction benefits under Section 80G, or must the trust separately obtain 80G approval after examining its activities and objectives?
The Revenue department argues that 12AA registration alone is not enough — each case under 80G demands fresh examination of the trust’s operations (whether it is genuinely charitable and not merely religious, etc.).
On the other hand, lower tribunals and the High Court in the cited case held that once 12AA registration is granted and valid, the trust cannot be denied 80G merely because of religious character, without cancellation of 12AA registration.
Key Legal Positions & Precedents on Section 12AA
According to expert commentary, a trust cannot assume that 12AA registration automatically gives 80G approval — the procedures, prior to recent amendments, were distinct for each approval.
Earlier tribunals have held that mentioning religious objects in the trust’s aims does not by itself justify denial of 80G approval; what matters is the real nature of activities and compliance.
The High Court in the case under review relied on a Gujarat High Court ruling (Hiralal Bhagwati v. CIT, 2000) and a Supreme Court judgment (ACIT v. Surat City Gymkhana, 2008) to support its view that valid 12AA registration limits further enquiry for 80G denial.
The SC Bench & Their Notice on Section 12AA Controversy
The bench of Justices J. B. Pardiwala and K. V. Viswanathan has issued notice on the petition and scheduled a hearing — the first step in determining the legal principle. The bench pointed out that the crucial consideration is whether the trust’s work is charitable or religious in nature, and that this will affect eligibility for 80G benefits.
About the Judges
- Justice J. B. Pardiwala – A senior judge of the Supreme Court known for tax and corporate law pronouncements.
- Justice K. V. Viswanathan – Also a noted jurist with experience in constitutional and commercial matters.
Their involvement underscores the significance of the issue for donors, trusts and the tax system.
Importance of This Ruling
1. Donors’ perspective – Many individuals and corporate donors make contributions to trusts hoping to avail deduction under 80G. Clarification on whether 12AA status suffices will affect the confidence in claiming such deductions.
2. Trusts’ perspective – Charitable institutions often invest time and resources to obtain registrations. If 12AA registration is sufficient for 80G, it simplifies compliance; if not, trusts will need to ensure full 80G approval processes.
3. Tax-department oversight – The ruling may define the limits of the department’s power to evaluate trust activities post-12AA registration.
4. Clarity in law – The disparity in lower courts’ decisions has led to uncertainty; the SC’s decision may establish a uniform standard.
5. Fiscal implications – Donation-driven funding for social and charitable work depends on incentives; this ruling could influence donation flows and trust mobilisation.
Way Forward
- The SC’s final verdict, which may either endorse the view that 12AA registration alone is sufficient or require separate 80G approval.
- Any guidelines or conditions attached by the SC setting out when 80G deduction can be granted, especially in cases with religious or sectarian activities.
- Implications on trusts that have 12AA but not 80G status — will they be retroactively affected?
- The impact on donors who have claimed 80G deductions based solely on 12AA registration — will their claims be upheld or challenged?
Practical Guidance for Trusts & Donors
- Trusts should ensure they apply for 80G approval in addition to 12AA registration, and maintain clear records of activities showing charitable (non-sectarian) nature.
- Donors should check that the trust has a valid 80G registration certificate, not merely 12AA registration, before relying on deduction.
- Keep evidence of donation receipts bearing 80G registration number and trust’s PAN.
- Be alert for updates once the SC decision comes, which may require retroactive compliance or correction.